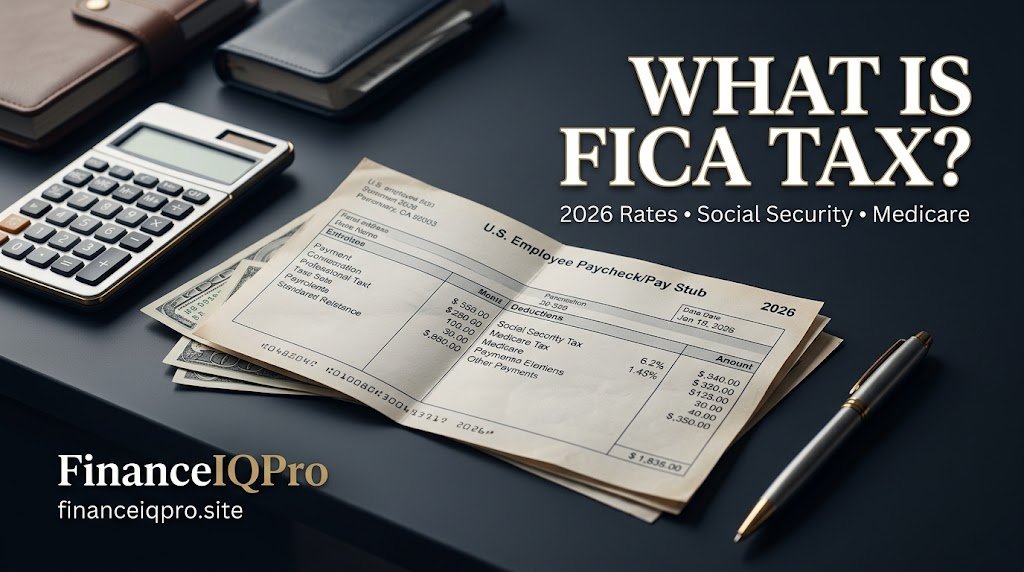
If you have ever looked at a paycheck and wondered why money is deducted for Social Security and Medicare, you have already encountered FICA tax. FICA stands for the Federal Insurance Contributions Act, the federal law that requires payroll taxes to help fund Social Security and Medicare. For most employees, FICA is automatically withheld from each paycheck by the employer.
FICA tax is different from federal income tax. Your federal income tax withholding depends on factors such as your income, filing status, and withholding elections, while FICA generally applies at specific payroll tax rates. In 2026, an employee generally pays 6.2% for Social Security and 1.45% for Medicare, for a combined employee FICA rate of 7.65%. Employers generally pay an additional matching 7.65%.
The rules become more important as income rises because Social Security has an annual taxable wage limit, while Medicare tax generally applies to all covered wages. Higher income employees can also be subject to an additional 0.9% Medicare tax.
Understanding FICA can make your pay stub easier to read, help you estimate take home pay, and explain why your employer’s labor cost is higher than your gross salary.
How Does FICA Tax Work?
FICA is essentially a payroll tax system divided into two major components: Social Security tax and Medicare tax. These taxes are collected from covered wages and used to finance federal programs that provide retirement, disability, survivor, and health insurance benefits.
For a typical employee in 2026, the employer withholds 6.2% of applicable wages for Social Security and 1.45% for Medicare. The employer generally contributes an equal amount. That means the combined employee and employer contribution is 15.3% before considering the different treatment of the Additional Medicare Tax.
The basic calculation for an employee can be summarized as:
Employee FICA = Social Security tax + Medicare tax
Employee FICA = 6.2% + 1.45%
Employee FICA = 7.65%
For example, if an employee earns $5,000 in covered wages during a pay period, the standard FICA withholding would be approximately $382.50, assuming the wages are subject to the standard rates and the employee has not reached the Social Security wage base.
That $382.50 is not the employee’s entire federal tax burden. Federal income tax, state income tax where applicable, and other deductions may also reduce the paycheck.
For 2026, the IRS confirms that the Social Security tax rate is 6.2% for both employees and employers, while the Medicare tax rate is 1.45% for each. Social Security has a $184,500 wage base for 2026, while Medicare does not have a wage base limit.
What Are the FICA Tax Rates for 2026?
The standard FICA rates are relatively straightforward, but understanding the individual components is important because Social Security and Medicare are treated differently.
| FICA component | Employee rate | Employer rate | 2026 wage limit |
|---|---|---|---|
| Social Security | 6.2% | 6.2% | $184,500 |
| Medicare | 1.45% | 1.45% | No limit |
| Standard total | 7.65% | 7.65% | Different rules apply |
The Social Security portion is subject to the annual taxable maximum. In 2026, the first $184,500 of covered earnings is subject to the 6.2% Social Security tax. Once an employee reaches that wage base, additional wages generally are not subject to the 6.2% Social Security tax for that calendar year.
Medicare works differently. There is no annual wage cap for the regular 1.45% Medicare tax. Someone earning $50,000 and someone earning $500,000 both generally owe the regular Medicare tax on their covered wages.
The Social Security Administration reports that the 2026 Social Security taxable maximum is $184,500. At the 6.2% employee rate, the maximum employee Social Security tax based on that wage base is $11,439.
These numbers can change in future years, so anyone calculating payroll taxes for a different tax year should use the rates and wage limits applicable to that year.
What Is the Social Security Portion of FICA?
The Social Security portion of FICA helps finance the federal Social Security system. Social Security provides several types of benefits, including retirement benefits, disability benefits, and benefits for qualifying survivors.
For employees, the Social Security tax rate is 6.2% in 2026. Employers generally pay another 6.2%, creating a combined employer and employee rate of 12.4%.
The important point is that the 6.2% employee tax does not continue indefinitely on every dollar earned during the year. The Social Security wage base limits the amount of earnings subject to this particular tax.
For example, consider an employee who earns $100,000 in 2026.
The Social Security calculation is:
$100,000 × 6.2% = $6,200
Now consider someone who earns $250,000.
The Social Security tax is generally calculated only on the first $184,500:
$184,500 × 6.2% = $11,439
The employee does not continue paying the regular 6.2% Social Security tax on the remaining $65,500.
This wage base rule is one of the biggest reasons why the FICA deduction on a high income worker’s paycheck can change later in the year.
The Social Security Administration describes $184,500 as the 2026 contribution and benefit base for covered earnings.
What Is the Medicare Portion of FICA?
The Medicare portion of FICA finances the Hospital Insurance component of Medicare. Unlike Social Security tax, regular Medicare tax does not have an annual wage ceiling.
The standard Medicare tax rate for an employee is 1.45% in 2026. The employer generally pays another 1.45%, producing a combined regular Medicare tax rate of 2.9%.
Suppose an employee earns $80,000 during the year.
The regular Medicare calculation is:
$80,000 × 1.45% = $1,160
If another employee earns $300,000, the regular Medicare calculation is:
$300,000 × 1.45% = $4,350
The Medicare tax continues to apply because there is no regular Medicare wage base.
Higher earners can face another payroll tax consideration: the Additional Medicare Tax. Employers are required to withhold an additional 0.9% from an employee’s Medicare wages once wages paid by that employer exceed $200,000 during the calendar year. There is no employer matching contribution for this additional 0.9% tax.
Importantly, the $200,000 employer withholding threshold is not the same thing as the ultimate tax liability threshold based on filing status. The Additional Medicare Tax is reconciled on the individual’s tax return when applicable.
How Is FICA Tax Calculated on a Paycheck?
Calculating standard employee FICA is easier than calculating federal income tax because the basic rates are fixed.
Imagine an employee earns $4,000 in gross wages during a paycheck.
Social Security:
$4,000 × 6.2% = $248
Medicare:
$4,000 × 1.45% = $58
Total FICA:
$248 + $58 = $306
The employee’s gross pay is $4,000, but approximately $306 would be withheld for standard FICA.
The employee would therefore have:
$4,000 − $306 = $3,694
before federal income tax, state and local taxes, retirement contributions, health insurance premiums, and other payroll deductions.
This example assumes all $4,000 is subject to the standard FICA rates and that the employee has not already reached the Social Security wage base.
A different result can occur when an employee receives bonuses, certain fringe benefits, commissions, tips, or other forms of compensation. Payroll systems must determine whether particular payments are treated as wages for Social Security and Medicare purposes.
For workers trying to understand their total paycheck deductions, it is useful to distinguish gross income from taxable wages, FICA wages, federal income tax withholding, and other deductions rather than treating every paycheck deduction as the same type of tax.
Why Does FICA Stop Increasing for Social Security but Not Medicare?
One of the most confusing parts of FICA is that Social Security and Medicare do not use the same wage rules.
Social Security has a taxable maximum. Medicare does not.
Suppose an employee earns $20,000 per month in 2026 and remains employed throughout the year. During the early months, the employee pays both Social Security and Medicare taxes on covered wages.
Once the employee’s year to date Social Security wages reach $184,500, the regular Social Security withholding generally stops for the rest of the calendar year. Medicare withholding continues.
This can create a noticeable increase in take home pay later in the year for certain high income employees. However, Medicare withholding does not disappear.
For example, assume an employee has already reached the Social Security wage base and then receives another $10,000 in covered wages.
Social Security:
$10,000 × 0% = $0
Regular Medicare:
$10,000 × 1.45% = $145
The employee may therefore see a smaller FICA deduction on that particular paycheck because the Social Security portion has stopped, while Medicare continues.
This distinction is also why high earners should not estimate annual payroll taxes simply by multiplying their entire salary by 7.65%.
What Is the Difference Between FICA Tax and Federal Income Tax?
FICA and federal income tax are both federal taxes, but they serve different purposes and are calculated under different rules.
FICA primarily refers to Social Security and Medicare payroll taxes. Federal income tax is a separate tax on taxable income and is generally subject to tax brackets, deductions, credits, filing status, and withholding elections.
The distinction can be seen on a typical pay statement. A paycheck may show separate deductions for:
- Social Security
- Medicare
- Federal income tax
- State income tax
- Retirement contributions
- Health insurance
- Other benefits or deductions
FICA is therefore not another name for federal income tax.
This distinction matters when estimating take home pay. An employee earning $60,000 does not simply lose 7.65% and then keep the remaining 92.35%. Federal income tax and potentially state or local taxes may also be deducted.
FICA also generally does not work like a traditional income tax deduction that reduces taxable income. Payroll withholding for Social Security and Medicare is a separate employment tax mechanism.
If you are estimating your overall tax burden, it can be useful to compare FICA with federal income tax withholding rather than combining the two into one percentage.
How Does FICA Work for Self Employed Workers?
Self employed workers generally do not have an employer paying the matching portion of FICA on their behalf. Instead, self employment tax generally covers both the Social Security and Medicare components.
The combined self employment tax rate is generally 15.3% before considering the special rules for calculating net earnings from self employment and the income tax deduction associated with the employer equivalent portion.
For 2026, the Social Security portion of self employment tax is 12.4% on applicable earnings up to the $184,500 Social Security wage base, while the Medicare portion is 2.9% on applicable earnings without a regular wage cap.
However, self employed individuals should not simply multiply business revenue by 15.3%.
Self employment tax is generally based on net earnings from self employment, subject to specific tax rules. Business expenses and other adjustments can affect the amount of income subject to the tax.
For example, a freelancer who receives $100,000 in payments may have less than $100,000 of net earnings if the person has legitimate deductible business expenses.
Self employed taxpayers may also need to consider estimated tax payments, the Additional Medicare Tax, and the deduction for part of the self employment tax when determining their overall federal tax situation.
Because self employment tax can become complicated, business owners and independent contractors with substantial income may benefit from reviewing their situation with a qualified tax professional.
Who Pays FICA Tax?
For a standard employee, both the worker and employer generally contribute to FICA.
The employee’s share is normally withheld from the paycheck. The employer contributes its own matching amount.
For the standard 2026 rates:
Employee Social Security: 6.2%
Employer Social Security: 6.2%
Employee Medicare: 1.45%
Employer Medicare: 1.45%
Combined employee share: 7.65%
Combined employer share: 7.65%
Combined standard employee and employer contribution: 15.3%
This does not mean that the employee personally pays 15.3% from the paycheck. The employee’s standard share is 7.65%, while the employer pays its matching share separately.
That distinction is especially important when comparing an employee’s salary with the total cost of employing that worker.
For example, if a worker earns a $70,000 salary, the employer generally has payroll tax costs beyond the $70,000 salary itself. The employer’s share of standard FICA would be approximately $5,355 before considering other employer payroll costs.
This is one reason an employer’s total labor cost can be higher than the employee’s stated salary.
Does FICA Tax Affect Your Social Security Benefits?
FICA taxes help finance Social Security and Medicare, but paying FICA does not mean you receive a dollar for dollar account balance similar to a bank savings account.
Social Security benefits are determined under federal rules that consider a worker’s earnings history and other eligibility factors. Social Security taxes collected today help finance benefits under the program’s structure rather than being placed into an individual investment account for each worker.
Your earnings record is therefore important. Employers report wages to the Social Security Administration, and those earnings can be used in determining future Social Security benefits.
The relationship between FICA taxes and future benefits is one reason workers should review their Social Security earnings record periodically and correct errors when necessary.
Medicare is different from an individual savings account as well. Paying Medicare payroll taxes helps finance the Medicare system, but eligibility and coverage depend on applicable federal rules.
Therefore, FICA should be viewed as a payroll tax contribution supporting federal insurance programs rather than as a personal retirement account.
What Happens If Too Much FICA Tax Is Withheld?
Payroll mistakes can happen, and certain workers can also have special situations involving multiple employers.
If you have multiple jobs, each employer generally applies Social Security withholding separately. As a result, your combined Social Security withholding can sometimes exceed the annual maximum amount that should ultimately apply to your total wages.
For example, an individual working for two employers may have each employer withhold Social Security tax on wages without knowing exactly what the other employer has paid.
When excess Social Security tax is withheld because of multiple employers, the excess may generally be claimed as a credit on the individual’s federal income tax return, subject to applicable rules.
The treatment can differ when one employer is an employer in a related group or when other special circumstances apply, so taxpayers should not assume every payroll over withholding situation is identical.
Medicare has different rules because there is no regular wage cap. The Additional Medicare Tax also involves annual filing status thresholds, meaning payroll withholding and final tax liability are not always identical.
If your W2 appears to show an unusual FICA amount, compare your year to date wages and withholding with your pay statements and W2. If the numbers still appear incorrect, contact your payroll department or tax professional.
How FICA Tax Appears on Your W 2
Your Form W 2 provides important information about wages and payroll taxes withheld during the year.
Several boxes are particularly relevant when reviewing FICA.
Box 1 generally reports wages subject to federal income tax withholding, while Social Security and Medicare have their own wage and tax boxes. Social Security wages and tax are generally reported in Boxes 3 and 4, while Medicare wages and tips and Medicare tax are generally reported in Boxes 5 and 6.
These amounts can differ.
For example, Social Security wages can be lower than Medicare wages for a high income worker because Social Security has an annual wage base while Medicare does not.
If your wages exceed the Social Security wage base, the amount shown as Social Security wages may be capped while Medicare wages continue to increase.
Reviewing your W 2 can help you understand whether your employer reported payroll taxes consistently with your pay statements.
If you discover an error, do not simply change the W 2 yourself. Contact the employer and request a corrected Form W 2 when appropriate.
How FICA Tax Changes Your Take Home Pay
FICA is one of the reasons your take home pay can be significantly lower than your advertised salary.
Consider an employee with an annual salary of $60,000.
Standard FICA would be approximately:
$60,000 × 7.65% = $4,590
That leaves:
$60,000 − $4,590 = $55,410
before federal income tax, state and local taxes, insurance premiums, retirement contributions, and other deductions.
This is a simplified illustration rather than a complete tax calculation.
For budgeting purposes, employees should generally build their spending plan around net income rather than gross salary. Someone earning $60,000 should not assume that $5,000 per month is available to spend simply because $60,000 divided by 12 equals $5,000.
The actual paycheck depends on withholding elections, pay frequency, benefits, retirement contributions, tax circumstances, and other deductions.
If you are trying to estimate your overall tax picture, FinanceIQPro’s Income Tax Slab Calculator can be a useful starting point for understanding income tax calculations, although FICA should be analyzed separately from federal income tax.
Common FICA Tax Examples
Understanding FICA becomes easier when you see how the rules work at different income levels.
An employee earning $40,000 in 2026 would generally owe approximately $2,480 in Social Security tax and $580 in Medicare tax, for total standard employee FICA of about $3,060.
An employee earning $100,000 would generally owe $6,200 in Social Security tax and $1,450 in Medicare tax, totaling $7,650.
An employee earning $184,500 would reach the Social Security wage base and would owe $11,439 in employee Social Security tax. Regular Medicare tax would be $2,675.25, producing $14,114.25 in standard employee FICA before considering any Additional Medicare Tax.
An employee earning $250,000 would generally still have a maximum Social Security tax of $11,439, while regular Medicare tax would apply to the full $250,000. That equals $3,625 in regular Medicare tax. Depending on the individual’s circumstances, Additional Medicare Tax may also apply.
These examples illustrate why the 7.65% figure is useful for basic paycheck calculations but becomes less precise as income increases.
FICA Tax vs. Self Employment Tax
FICA and self employment tax are closely related, but they generally apply in different employment situations.
Employees typically split the standard Social Security and Medicare burden with their employer. The employee pays 7.65%, and the employer generally pays another 7.65%.
Self employed individuals generally cover both sides through self employment tax. This is why the headline self employment tax rate is generally 15.3%.
However, that does not mean a self employed person always pays exactly 15.3% of business revenue.
The tax is based on applicable net earnings under self employment tax rules, and there are adjustments and deductions that can affect the calculation.
A freelancer making $80,000 in gross payments could therefore have a very different self employment tax calculation from an employee earning an $80,000 salary.
Business owners should also distinguish self employment tax from federal income tax. They are separate parts of the federal tax system and can both affect the amount a taxpayer ultimately owes.
Why Understanding FICA Matters for Employees and Business Owners
For employees, understanding FICA helps explain paycheck deductions and improves salary comparisons. Two jobs with identical gross salaries can still produce different take home pay because of benefits, retirement contributions, withholding elections, and other deductions.
For high income employees, understanding the Social Security wage base can explain why the paycheck deduction changes during the year.
For self employed workers, understanding FICA related taxes is even more important because there is no traditional employer withholding the employee’s share and paying a matching contribution.
For business owners, payroll tax compliance is a significant responsibility. Employers generally must withhold the employee’s share, contribute their employer share, report employment taxes, and deposit taxes according to applicable federal requirements.
The IRS provides detailed employer guidance through Publication 15 and related employment tax resources.
For anyone preparing a personal budget, calculating FICA is also useful because it provides a more realistic estimate of take home income.
What FICA Tax Does Not Include
The phrase FICA tax is sometimes used too broadly. Not every payroll related tax is FICA.
FICA generally refers specifically to Social Security and Medicare taxes.
It does not include federal income tax withholding.
It also does not automatically include federal unemployment tax. FUTA is a separate federal payroll tax system generally paid by employers.
State unemployment taxes are also separate.
State income taxes and local income taxes are separate from FICA as well.
This distinction is important because a pay stub may contain several tax deductions that look similar but have different purposes and rules.
When evaluating a paycheck, separate deductions into categories rather than treating every government deduction as FICA.
Doing so makes it easier to understand your true tax burden and identify unusual withholding.
How to Estimate Your FICA Tax for 2026
For a standard employee, estimating FICA can be done in a few basic steps.
First, determine your covered wages.
Second, calculate Social Security tax at 6.2% until the applicable 2026 wage base of $184,500 is reached.
Third, calculate regular Medicare tax at 1.45% on covered wages, with no regular wage ceiling.
Fourth, determine whether Additional Medicare Tax could apply based on your income and filing circumstances.
For someone earning less than $184,500 with standard covered wages, the basic estimate is:
Annual wages × 7.65%
For example:
$75,000 × 7.65% = $5,737.50
This represents an estimated standard employee FICA amount.
For someone earning more than $184,500, the calculation needs to separate Social Security and Medicare.
For example, with $220,000 of covered wages:
Social Security:
$184,500 × 6.2% = $11,439
Regular Medicare:
$220,000 × 1.45% = $3,190
Standard FICA:
$11,439 + $3,190 = $14,629
Additional Medicare Tax may potentially increase the final amount depending on the taxpayer’s circumstances.
The IRS and SSA should be used as the final authority for exact tax calculations, especially when compensation includes bonuses, tips, multiple jobs, self employment income, or special compensation.
Frequently Asked Questions About FICA Tax
What is FICA tax in simple terms?
FICA tax is a federal payroll tax that funds Social Security and Medicare. For a typical employee in 2026, the employee portion is 7.65%: 6.2% for Social Security and 1.45% for Medicare.
How much is FICA tax in 2026?
The standard employee FICA rate is 7.65% in 2026. Social Security is 6.2% on covered wages up to $184,500, while Medicare is 1.45% on all covered wages. Higher income employees may also be subject to the 0.9% Additional Medicare Tax.
Is FICA the same as federal income tax?
No. FICA and federal income tax are separate taxes. FICA primarily covers Social Security and Medicare payroll taxes, while federal income tax is calculated under the federal income tax system.
Does the employer pay FICA tax too?
Yes. For standard employees, the employer generally matches the employee’s 6.2% Social Security tax and 1.45% Medicare tax. The employer’s standard FICA share is therefore generally 7.65%.
Why does Social Security tax stop during the year?
Social Security has an annual taxable wage base. In 2026, the wage base is $184,500. Once covered wages reach that amount, the regular Social Security tax generally stops for the rest of the calendar year.
Does Medicare tax have a wage limit?
No. Regular Medicare tax does not have an annual wage base. The 1.45% employee Medicare tax generally continues to apply to covered wages regardless of how high the employee’s earnings become.
What is the Additional Medicare Tax?
The Additional Medicare Tax is an extra 0.9% Medicare tax that can apply to wages and other applicable income above thresholds determined by tax law and filing status. Employers generally begin withholding it from an employee’s wages after wages paid by that employer exceed $200,000 during the calendar year.
Do self employed people pay FICA tax?
Self employed individuals generally pay self employment tax rather than employee FICA withholding. The combined Social Security and Medicare rate is generally 15.3% before considering the special rules and adjustments that apply to self employment income.
Can you avoid FICA tax?
Most employees cannot simply opt out of FICA. Whether wages are subject to Social Security and Medicare taxes depends on employment status, the type of compensation, and specific provisions of federal tax law. Certain narrow statutory exceptions exist, but they do not apply to most workers.
Why is my FICA withholding different from my coworker’s?
FICA withholding can differ because employees may have different wages, bonuses, tips, multiple jobs, year to date earnings, or other circumstances. High earners may also reach the Social Security wage base during the year, causing the Social Security portion of withholding to stop while Medicare continues.
Conclusion
FICA tax is one of the most important payroll taxes for U.S. workers because it directly affects every paycheck and helps finance Social Security and Medicare. For a typical employee in 2026, the standard employee rate is 7.65%, consisting of 6.2% Social Security tax and 1.45% Medicare tax.